Commercial Property Damage Checklist: Insurance, Safety, and Restoration Steps
A commercial property damage checklist begins with protecting people, contacting emergency services when required, restricting access, notifying the insurer, and documenting the loss before cleanup changes the original conditions.
The business can then arrange an emergency damage assessment, protect records and equipment, track expenses, plan temporary operations, and develop a coordinated restoration scope.
Immediate Commercial Property Damage Checklist
The first hour can affect employee safety, loss documentation, repair planning, and how quickly the business can resume operations. Use this checklist to organize the immediate response.
- Evacuate people from unsafe areas.
- Call emergency services if an active hazard exists.
- Account for employees, visitors, customers, and contractors.
- Prevent entry into damaged sections.
- Contact the property owner or building manager.
- Notify the insurer or insurance broker promptly.
- Record the date, time, and known details of the incident.
- Photograph visible damage from a safe location.
- Ask before discarding damaged property.
- Arrange qualified emergency mitigation where appropriate.
- Track every loss-related and repair-related expense.
- Prepare a temporary operations or business-continuity plan.
Do not enter an unsafe building or attempt electrical, structural, fire, water, sewage, or hazardous-material work without qualified assistance.

Step 1: Protect Employees, Customers, and Visitors
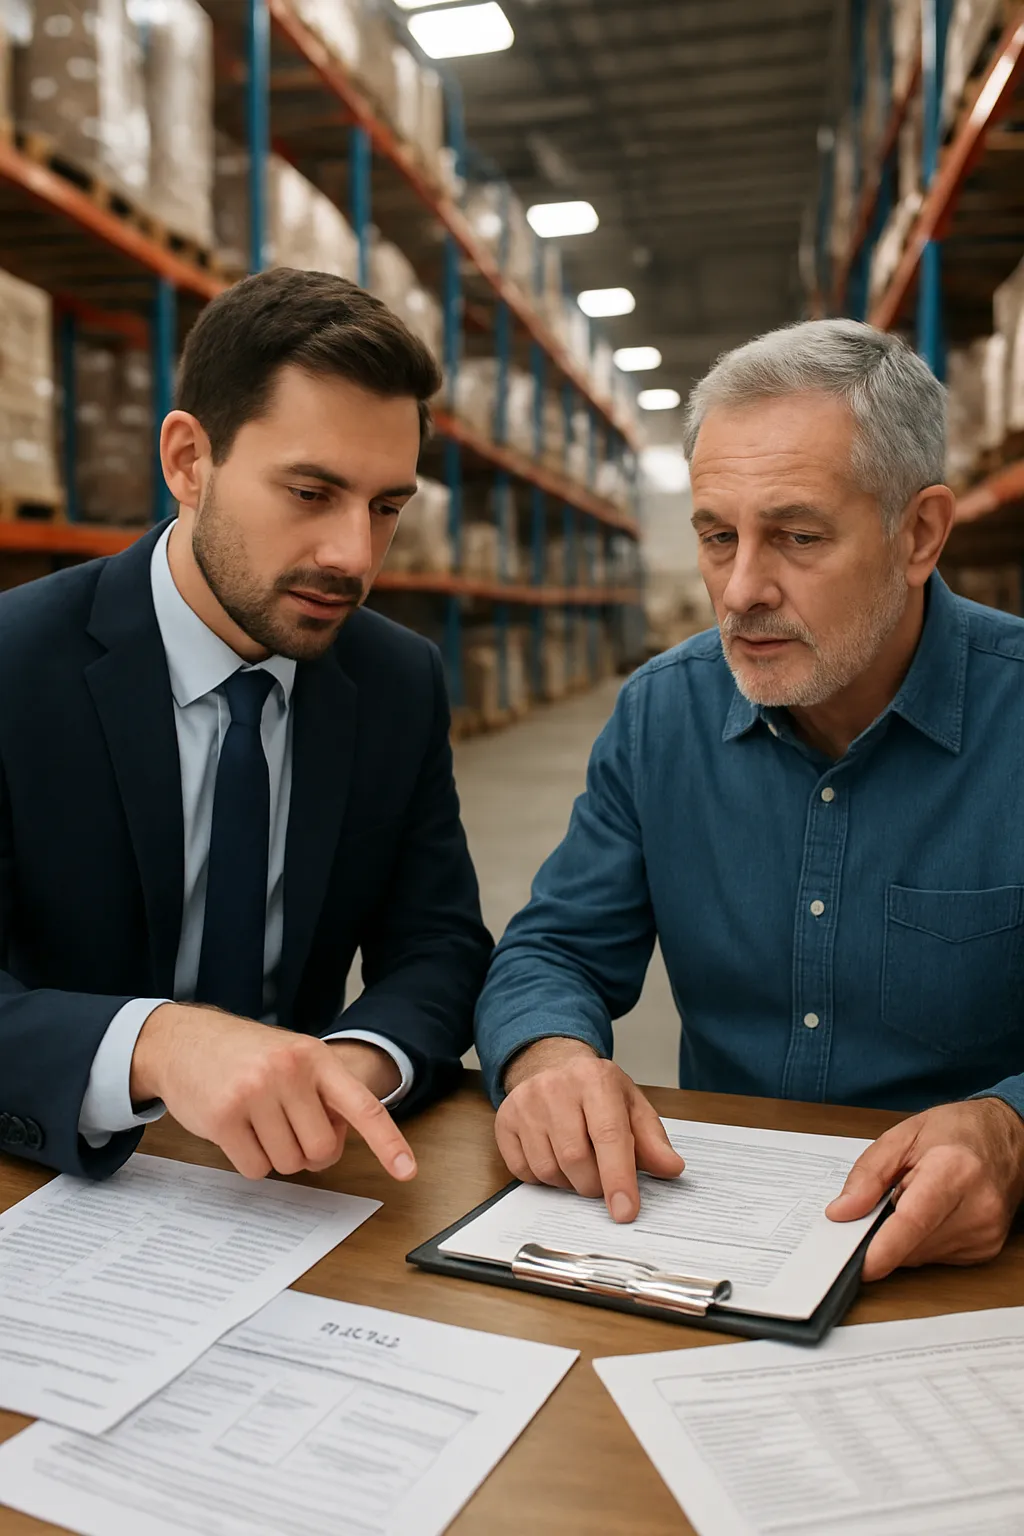
The first decision is whether the affected space is safe to occupy. Commercial buildings may contain hazards that are not immediately visible.
- Unstable ceilings, walls, roofs, shelving, or stored materials
- Water near electrical systems or powered equipment
- Smoke, soot, dust, or contaminated indoor air
- Broken glass, sharp metal, and exposed fasteners
- Wet floors, damaged stairs, and blocked exits
- Gas, chemical, refrigerant, or fuel releases
- Sewage-contaminated water
- Damaged sprinklers, alarms, or fire-protection equipment
- Moisture conditions that may support mould growth
Follow emergency-authority instructions. Do not restore power, move structural debris, climb onto a roof, or enter a restricted area simply to obtain photographs.
The Canadian Centre for Occupational Health and Safety explains that a workplace emergency response plan should address foreseeable emergencies, required actions, communication, evacuation, and available resources.
Establish a Controlled Area
Use barriers, signs, locked doors, or security personnel to keep employees and customers away from damaged sections. Maintain an entry record showing who entered, why they entered, and when they left.
If an unaffected part of the property may remain open, confirm that ongoing operations will not expose people to water, dust, unstable materials, poor air quality, construction traffic, or interrupted safety systems.
Partial occupancy should be based on actual site conditions. Emergency officials, engineers, electricians, environmental professionals, municipal authorities, or other qualified specialists may need to determine whether continued use is appropriate.
Restrict access
Prevent employees, customers, and unauthorized contractors from entering damaged areas.
Record entries
Maintain a simple log of every person authorized to enter the controlled area.
Protect safe routes
Keep exits, delivery routes, fire equipment, and emergency access unobstructed.
Reassess conditions
Building conditions can change as water moves, materials dry, or damaged components shift.

Step 2: Stop Ongoing Damage When It Is Safe
Commercial losses can worsen when water, wind, temperature changes, smoke residue, or unauthorized access continues to affect the property.
- Shutting off a water supply when authorized and safe
- Boarding a broken window, door, or wall opening
- Installing temporary roof protection
- Extracting standing water
- Moving unaffected stock away from damp areas
- Providing temporary heat or dehumidification
- Securing damaged doors, gates, or fencing
- Separating wet materials from unaffected materials
A qualified provider of emergency restoration services in Regina can assess urgent stabilization and building-protection needs. Proposed work should still be coordinated with the building owner and insurer.
Emergency work may reduce further damage, but it does not confirm that the expense will be insured. Coverage depends on the cause, policy terms, exclusions, limits, deductibles, and the insurer’s assessment.
Step 3: Notify the Right Parties
A commercial property loss may involve more contacts than a residential claim. Create one contact sheet so instructions do not become scattered across calls, messages, and emails.
- Emergency services
- Property owner or commercial landlord
- Building or facilities manager
- Insurance broker and insurer’s claims department
- Corporate risk manager
- Security and access-control provider
- Utility companies
- Alarm or fire-protection company
- Restoration contractor
- Environmental, structural, or engineering professionals
- Critical suppliers and customers
- Municipal or regulatory authorities where required
The Insurance Bureau of Canada recommends notifying the insurer promptly and organizing information related to the loss. Its guide explains how to file a business insurance claim.
What to tell the insurer
- Business and policyholder name
- Address of the damaged property
- Date and approximate time of loss
- Known type of incident
- Areas that appear affected
- Immediate safety concerns
- Emergency measures already taken
- Whether operations have stopped
- Building owner’s contact details
- Police, fire, or incident report number
Avoid guessing about the cause or repair cost. State what is known, identify what remains uncertain, and explain which professionals are assessing the property.
Review the Policy Without Assuming the Outcome
Businesses reviewing how their policy might respond can start with AnyInsurance’s commercial property insurance information.
Review the reported cause, deductibles, limits, exclusions, valuation provisions, endorsements, property descriptions, proof-of-loss requirements, and any duties that apply after a loss.
A contractor can inspect, document, estimate, mitigate, and repair physical damage. The insurer determines whether the policy responds and which amounts are approved.
Step 4: Complete a Damage Documentation Checklist
Good records help the business, building owner, insurer, adjuster, and restoration contractor understand what happened. Begin documenting as soon as conditions are safe.
Photograph and record
- Wide views of every affected room
- Close views of damaged materials
- Water lines and visible moisture
- Damaged inventory and equipment
- Entry points affected by wind or impact
- Exterior walls, roof edges, and drainage areas
- Product labels, model numbers, and serial numbers
- Temporary protection before and after installation
Never enter a dangerous area to obtain a better photograph. Safety restrictions take priority over documentation.

Create a Written Inventory
For damaged stock, furniture, machinery, electronics, tools, or customer property, create a structured inventory that can be updated as items are inspected.
- Item description
- Brand and model
- Serial or internal asset number
- Approximate purchase date
- Original purchase price
- Quantity affected
- Observed condition after the event
- Current location
- Inspection or disposal status
- Supporting receipt, invoice, or accounting record
Some damaged items may need inspection, testing, salvage review, or retention as evidence. Remove an item immediately only when qualified instructions identify a safety or health reason.
Preserve Business and Claim Records
- Insurance policies and endorsements
- Lease and landlord correspondence
- Incident, fire, and police reports
- Contractor estimates and repair scopes
- Moisture readings and inspection reports
- Photographs and video files
- Inventory and asset records
- Invoices and proof of payment
- Payroll and sales records
- Temporary-location expenses
- Customer cancellations or delayed orders
- Equipment rental and transportation expenses
AnyInsurance’s business insurance information can help owners understand how property, liability, auto, interruption, and other commercial policies may fit into broader risk planning.
Step 5: Understand the Emergency Damage Assessment
An emergency damage assessment identifies visible loss, active hazards, affected systems, and work that may be required to stabilize the property. Several professionals may contribute separate findings.
Restoration contractor
May assess water migration, wet materials, smoke residue, contamination, demolition, drying requirements, temporary protection, and repair sequencing.
Electrician
May assess panels, wiring, outlets, fixtures, controls, and equipment exposed to water, heat, smoke, or impact.
Structural professional
May evaluate walls, beams, columns, foundations, roof systems, or storage systems that appear displaced or weakened.
Environmental professional
May assess suspect asbestos, lead, mould, sewage, chemicals, or other hazards before materials are disturbed.
Equipment specialist
May test commercial kitchens, manufacturing systems, medical equipment, refrigeration, or technology before reuse.
Insurance adjuster
Reviews the loss and submitted information for the insurer but does not replace technical assessments required for safe repair work.

A contractor’s report describes physical conditions and possible repair requirements. The insurer separately determines coverage under the policy.
Step 6: Separate Mitigation, Restoration, and Improvements
Commercial recovery often contains three different categories of work. Separating them makes contractor scopes, insurer reviews, and business decisions easier to understand.
| Work category | Purpose | Possible examples |
|---|---|---|
| Emergency mitigation | Protect people and reduce additional damage. | Extraction, temporary roof covering, board-up, shoring, temporary heat, security, and controlled access. |
| Property restoration | Repair damage and return affected areas to an agreed condition. | Demolition, drying, framing, roofing, drywall, flooring, painting, mechanical, electrical, and finish work. |
| Optional improvements | Change or improve the property beyond the loss-related repair scope. | Layout changes, premium finishes, additional equipment, expanded renovations, or upgrades to unaffected areas. |
Businesses in Regina can review commercial restoration services when seeking a contractor capable of coordinating mitigation, reconstruction, and multiple repair trades.
Step 7: Review the Restoration Scope Before Work Expands
A written scope should explain what will be inspected, protected, removed, dried, cleaned, repaired, replaced, or tested.
- Rooms, floors, and building areas included
- Measurements and quantities
- Materials and finish assumptions
- Temporary protection and access controls
- Required testing and professional reports
- Labour, equipment, and monitoring
- Permit and inspection responsibilities
- Subcontracted trades
- Waste handling and disposal
- Project phases and estimated schedule
- Change-order process
- Exclusions and unresolved items
The property owner, insurer, adjuster, and contractor may not describe or price the scope in the same format. Material differences should be documented and discussed before major reconstruction proceeds.
Step 8: Protect Business Operations
Property damage can interrupt sales, deliveries, production, appointments, customer access, data systems, and recordkeeping. Prepare an operational impact list alongside the physical repair plan.
- Departments or tenant spaces unable to operate
- Critical equipment that is unavailable
- Orders, appointments, or deliveries that may be delayed
- Customers and suppliers who require updates
- Staff who can work remotely
- Functions that can move to another location
- Data and communication systems requiring restoration
- Extra costs needed to maintain partial operations
- Daily changes in sales, bookings, or production
If the policy includes interruption coverage, the insurer may request sales, payroll, expense, and accounting records. Review the general purpose of business interruption insurance, while remembering that a specific loss must satisfy the actual policy terms.
Step 9: Track Decisions and Expenses
Create one secure loss file with restricted access. Use consistent folder names so the business can locate evidence, approvals, and costs without searching across personal inboxes.
- Policy and claim information
- Safety and incident reports
- Photographs and video
- Professional and contractor reports
- Estimates and written scopes
- Invoices and proof of payment
- Damaged-property inventory
- Business interruption records
- Emails and claim notes
- Approvals and change orders
Maintain a communication log
Record the date, time, person, organization, subject, instruction, and next action for each important conversation. After a significant call, send a short email confirming what was discussed.
Separate expense categories
Track emergency mitigation, permanent repairs, interruption expenses, and optional improvements separately. This helps prevent elective upgrades from being mixed into the claimed restoration work.
Review contractor risk separately
Property owners hiring trades can also review contractor insurance considerations when confirming certificates, subcontractor arrangements, and project requirements.
Representative Commercial-Loss Example
Consider a retail business that discovers water entering through a storm-damaged roof.
- Protect people The manager closes the affected sales area, redirects customers, and obtains professional guidance about whether the remaining space is safe.
- Notify the relevant parties The business contacts its landlord, broker, insurer, security provider, and restoration contractor.
- Document the conditions Staff photograph the affected sales floor from a safe location and create an inventory of wet or damaged stock.
- Reduce further damage A qualified contractor installs temporary protection, assesses water migration, and begins authorized mitigation and drying work.
- Maintain partial operations Online-order pickup moves to an unaffected entrance, while closed areas remain separated from customers.
- Track the impact The business records sales changes, extra labour, temporary signage, equipment rentals, and other loss-related expenses.
Protect people, notify the appropriate parties, document the original conditions, reduce further damage, and then build the repair plan. This example does not predict whether any portion of a specific loss will be covered.
Common Mistakes After Commercial Property Damage
A rushed response can create safety, documentation, and project-management problems. Avoid these preventable mistakes.
- Entering an unsafe building
- Delaying insurer notification
- Discarding property before documenting it
- Cleaning away evidence without photographs
- Hiring unqualified workers for hazardous tasks
- Accepting a vague repair scope
- Mixing elective upgrades into a restoration estimate
- Failing to record interruption and extra expenses
- Relying only on verbal approvals
- Assuming every emergency expense will be covered
- Restarting equipment before professional inspection
Commercial Insurance and Emergency-Planning Resources
Use these Canadian resources for additional information about workplace emergency planning, business claims, and commercial coverage categories.
- Insurance Bureau of Canada: Types of Business Insurance General information about commercial property, interruption, liability, auto, cyber, and other business coverage. Read resource →
- Canadian Centre for Occupational Health and Safety Emergency response planning guidance covering risk assessment, procedures, training, recovery, and continuity. Review guidance →
Frequently Asked Questions
Direct answers to common questions businesses ask after property damage.
What should a business do first after property damage?
Protect people and follow emergency instructions. Restrict access, notify the property owner and insurer, document visible conditions safely, and arrange qualified mitigation when necessary.
Can cleanup begin before the adjuster arrives?
Urgent work may be necessary to protect people or reduce further damage. Contact the insurer promptly, document the original conditions, retain invoices, and ask what authorization or evidence is required.
Should damaged inventory be discarded?
Not automatically. Photograph and inventory it first, then ask the insurer or adjuster whether inspection, testing, salvage review, or retention is required.
Who decides whether the building is safe?
The answer depends on the hazard. Emergency officials, engineers, electricians, environmental professionals, municipal authorities, or other qualified specialists may be involved.
Does commercial property insurance pay for every repair?
No. Coverage depends on the cause of loss, policy language, exclusions, limits, deductibles, valuations, endorsements, and the insurer’s assessment.
When should a restoration contractor be contacted?
Contact a qualified contractor when urgent protection, water removal, drying, contamination control, demolition, or coordinated repairs may be required. Notify the insurer and document instructions to proceed.
Has Your Commercial Property Been Damaged?
Review the policy, organize the incident details, document the property safely, and request guidance about the appropriate insurance contact or coverage-review process.
For insurance guidance, start with the AnyInsurance business insurance homepage. For construction and restoration planning in Regina, visit KB Better Construction to review available services and request a property assessment.